SIDBI Pulls ₹6,000-Crore Bond Sale As Yields Harden
State-run lender withdraws three-year issuance after investor bids exceeded acceptable pricing amid rising benchmark yields
Synopsis
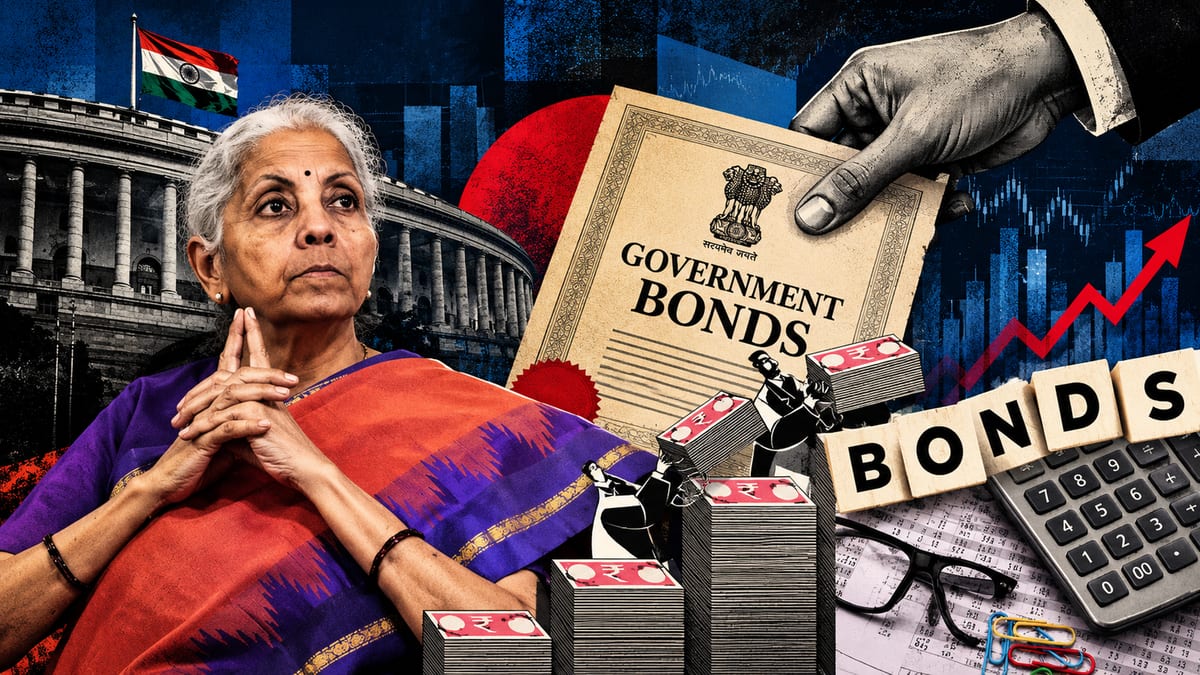
The Small Industries Development Bank of India (SIDBI) halted a planned bond sale of ₹6,000 crore for three years after the amount of bids received exceeded its comfortable cut-off yield. The episode was a part of an increase in hardening in Indian bond markets amid a rise in the yield of benchmark government securities.
The Withdrawal
SIDBI had cancelled its bond sale of ₹6,000 crore on Thursday because the cut-off yield was too high for the issuer and the investors demanded more risk premium in the three-year tenor. Market participants had offered bids around 7.85 per cent for the base issue of ₹1,000 crore and 7.97 per cent for the entire issue size of ₹6,000 crore.
The Pricing Gap
The difference between what the issuers hoped for and what the investors wanted was the key. The investors' pricing was known to be 5-10 basis points premium to similar AAA rated PSU rates in the secondary market, participants said.
Prospective investors were looking for cut-off yield between 7.85 per cent to 7.97 per cent, which is 5 to 10 basis points higher than similar AAA-rated Public Sector Undertaking bonds are now being sold in the secondary market.
Further information on hardening yields is available on the Backdrop page
Withdrawal was not an isolated event. The price was because of the increase in the yield on the 10-year government bond in the two previous trading sessions, by roughly 8 basis points.
It reflects the overall downward trend in debt markets for the week as well as falling equity benchmarks in the country for the seventh consecutive weekly period, in the wake of high crude prices and increased global yields.
Expert Assessment
Whether SIDBI's decision today will play to its advantage or disadvantage will depend on the decision on the rates as well as on the liquidity measures, the comments and forward guidance by the RBI in the October policy, said Venkatakrishnan Srinivasan, founder and managing partner of Rockfort Fincap LLP.
Not the First Such Cancellation
SIDBI's withdrawal is part of a pattern by public-sector issuers as they grapple with a confusing rate environment. Both the Power Finance Corporation and SIDBI had suspended their bond issuance plans worth ₹11,500 crore in December 2025 due to bids received by them at a higher rate than what they were willing to offer, despite a recent reduction in the rates by the RBI.
Market participants commented, order books were healthy, but the bids were at a slightly higher yield as investors matched their pricing with the new sovereign benchmarks as opposed to the lower levels the issuers had priced in.
Avoid: Comparing with previous successful raises
Fundraising has been a roller coaster ride for SIDBI throughout the year. Earlier, SIDBI had raised ₹7,866 crore through bonds which had a coupon rate of 7.22 per cent and were due in a little more than three years, against the target of raising ₹8,000 crore.
That's a stark example of the price mismatch that has occurred as yields have toughened around the globe this year.
Why It Matters
MSME lenders, such as SIDBI, can depend on bond-market access to enable onward-lending. Even as smaller-ticket loans have increased their share, India's small business credit portfolio stands steady at ₹47.8 lakh crore despite its growth slowing in the face of a higher base.
The high cost or disruptions of funding for institutions such as SIDBI will have downstream effects on credit availability for the micro, small and medium enterprises sector which the government has been stressing as key to employment creation.